Why gamma runs the market.
And where it shows up on your chart.
There are players in the market who don’t get to choose when they buy and sell. Options dealers are contractually forced to hedge, and the force that dictates when and how much is called gamma. Their forced buying and selling concentrates at specific prices — and those prices are computable. Every night, from end-of-day options open interest, Trade Tracer computes dealer gamma exposure (GEX) for SPY, QQQ and 400+ names, and locks the levels for every ticker before the open. Those locked levels are the foundation, and they don’t change during the session. This page explains every piece — what each level means and how to read it.
Read it once front to back, then come back to specific sections when you want to dig deeper.
The market has forced buyers and sellers. You can know where.
Most of what happens in a trading day is people choosing to buy and sell. But a meaningful slice of every session is different: it’s options dealers hedging, and they don’t get to choose. When a dealer takes the other side of an option trade, they take on risk they’re not in business to hold — so they offset it by buying or selling the stock, mechanically, by formula. Millions of contracts, every session.
Here’s why that matters to you: forced flows behave differently from voluntary ones. A discretionary buyer can change their mind. A dealer hedging a book cannot — the math tells them when to act and how much, and the math is tied to specific strike prices. That means their buying and selling concentrates at knowable levels. When price approaches one, someone very large is obligated to show up and trade there, whether they like it or not.
Everything Trade Tracer publishes — the Gamma Flip, the Call Wall and Put Wall, the Gamma Nodes, the GEX-by-strike views, the Dealer Flows — is a view of that one phenomenon: where the forced money sat at last night’s close, and what it’s obligated to do next session. The foundation is end-of-day: the engine computes after the close, locks the levels before the open, and they hold still all session.
Why dealers must show up at certain prices
Start with what an option actually is to the dealer who sold it: a promise whose risk changes as the stock moves. The measure of how much stock an option behaves like is called delta. The measure of how fast that delta changes as price moves is called gamma. That’s the whole definition — gamma is the speedometer on a dealer’s risk.
A dealer’s job is to stay neutral. So every time price moves and their delta changes, they must trade stock to get flat again — and gamma dictates exactly how much. The crucial detail: gamma is not spread evenly across prices. It bunches around strikes where lots of options are open, and it’s largest when price is near those strikes and expiration is close. That bunching is why the forced trading shows up at specific levels instead of everywhere at once. A strike with billions of dollars of open options behind it is a price where dealers, mechanically, must transact in size as price approaches.
Which direction they’re forced to trade depends on which side of their book dominates. In one zone their hedging pushes against the prevailing move — selling rallies, buying dips — which dampens volatility and makes levels act like walls. That’s positive gamma: days tend to chop and mean-revert. In the other zone their hedging pushes with the move — selling as price falls, buying as it rises — which amplifies it. That’s negative gamma: days tend to trend and swing wider. It’s how crashes cascade and how squeezes rip. Same mechanic, opposite effects, and the dividing line between the two zones is computable: that line is the Gamma Flip.
Trade Tracer computes its levels from end-of-day options open interest every night. Every level is computed after the close, locked before the open, and never changes during the session.
The regime line
The Gamma Flip is the price where net dealer gamma flips sign — from positive (hedging dampens moves) to negative (hedging amplifies them). It’s drawn in purple on every chart, computed nightly from end-of-day options open interest, and locked before the open.
How to read it
Price above the Gamma Flip — positive gamma: dealers hedge against the move. Rallies get sold, dips get bought — mechanically — so days tend to chop and mean-revert. Violent moves in either direction tend to get absorbed.
Price below the Gamma Flip — negative gamma: dealers hedge with the move. Drops pick up speed as dealer selling adds to them; squeezes rip harder than they otherwise would. Days tend to trend and swing wider, in both directions, which is why position size tends to matter more here.
Price at the Gamma Flip: transition. The regime is contested, and the framework treats the next decisive close on either side as the tell.
The honest edge case
Some days the options surface is one-sided and there is no meaningful flip near price — the market is deep in one regime. When that happens, the chart says so: “no nearby flip.” We don’t manufacture a line just so the chart has one. An honest blank is worth more than a fabricated level.
The strikes dealers defend
Dealer hedging is not spread evenly across prices. It piles up at specific strikes — the ones where the most contracts are open and the gamma on those contracts is largest. Two of those strikes matter more than the rest, and the chart draws both.
The Call Wall is the strike above price holding the most call gamma, counted across every expiration out to 45 days. Most of those calls were sold by customers (covered calls, call overwrites), which leaves dealers long them. When price rallies into that strike, dealers sell stock to stay neutral — so rallies tend to stall there rather than run through. Think of it as the ceiling of the dealer’s comfort zone.
The Put Wall is the mirror below price: the strike holding the most put gamma. Those puts were mostly bought as protection. Price has tended to find buyers near it — partly dealers adjusting hedges, partly because that is where the insurance everyone bought starts paying off. It is the floor of the comfort zone.
Between the two walls, hedging tends to dampen moves. Outside them, it stops helping and can start amplifying. “Between the walls” and “outside the walls” are different kinds of day.
Actual strikes, not averages
Every number the engine publishes is a strike that exists in the options chain. We do not average the ten biggest strikes into a price that nobody is positioned at. A Call Wall at $750 means $750 is where the call gamma sits — and $750 is where dealers hedge. Earlier versions of these levels (the Weekly and Monthly Walls) were weighted averages of a zone; price would react at the strike inside the zone while the line sat a few dollars off. That is why the engine was rebuilt around strikes.
How to read them
Price between the walls: the base case is contained movement. The Call Wall is the first overhead reference; the Put Wall is the first reference underneath. First touches tend to produce a reaction.
Price pressing a wall: the market is testing the heaviest hedging on that side. A stall is the common outcome; a decisive close through it has tended to mean positioning has shifted, and the next night’s lock will show where the new wall is.
Walls close together: hedging is stacked tightly around price — a pinned, range-bound session is the base case. Walls far apart: there is room to travel, and the Gamma Nodes in between become the working levels.
Repeated tests: each test consumes some of the positioning behind the level. A wall hit three or four times in a week is weaker than one being touched fresh.
What they’re not
- Not buy or sell signals — measured reference levels
- Not price targets — price has no obligation to reach them
- Not guarantees — levels tend to matter; some days they don’t
- Not stops — your stop belongs to your position size and risk tolerance, not to our math
The rest of the map
The walls are the two biggest strikes. They are not the only ones that matter. The solid grey lines on the chart are Gamma Nodes: the other strikes where dealer gamma piles up, counting calls and puts together across every expiration from 1 to 45 days out. Every node is an actual strike.
Which ones get drawn
The chart draws up to five: the heaviest nodes that sit inside today’s expected-move range, the stretch price is likely to cover. A strike that is already the Gamma Flip, a wall or the 0DTE Pin is left off, because that line already carries its own label. Fewer than five lines means fewer strikes carried real weight inside the range.
What the thickness means
Thickness is weight. The heaviest node on the chart is drawn about five pixels thick and the brightest; the others scale down from it, to a one-pixel line at the light end. A thick line means a lot of hedging is parked at that strike; a thin one means some. On a computer, hover a line to see the strike, its dollars of gamma, and whether it is call-heavy or put-heavy. The bars in the GEX map on the right of the chart show the same strikes, so a thick line always has a long bar beside it.
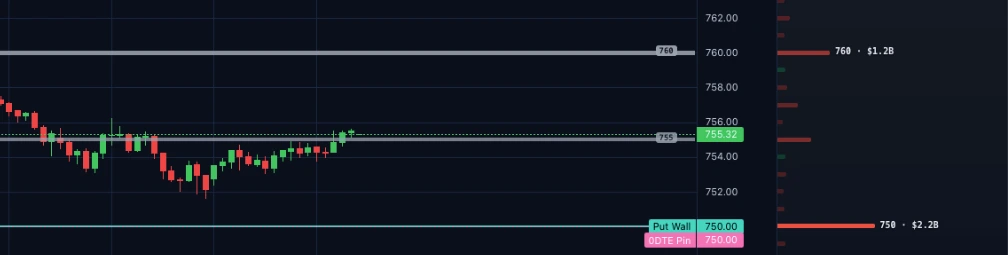
How to read them
Nodes are where price tends to react on the way between the walls: a pause, a bounce, a pin into the close. The nearest node above and below price are the levels to watch first; the walls are what they lead to. Thicker nodes have tended to produce the bigger reactions.
In positive gamma, a node tends to act like a speed bump: price slows, often stalls, and the thicker the line the more likely the stall. In negative gamma, a node is more of a checkpoint: once price breaks through one, the move tends to travel to the next node rather than snap back. Either way, the empty space between two nodes is where price tends to move fastest, because little hedging sits there to slow it down.
Thickness is relative to the other nodes on the same chart, on the same day. To compare a node with yesterday’s or with another ticker’s, use the dollar figure on hover or the GEX Ladder.
The 0DTE Pin
Same-day options carry enormous gamma for the few hours they have left, and that gamma collapses at the close. The 0DTE Pin is the strike with the most gamma on today’s expiration alone. It is drawn as its own dashed line rather than mixed into the walls, because it describes a different clock: price has tended to gravitate toward it into the afternoon, and it means nothing tomorrow. On names with no same-day expiration, the pin is the nearest expiration’s heaviest strike.
Where the weekly and monthly views went
The walls and nodes are built from every expiration in the next 45 days at once, because a strike with gamma stacked across four expirations is a bigger anchor than the top strike of any single one. If you want to see which expirations built a node, the Gamma Map and GEX tab let you toggle expirations on and off — that is the honest version of “weekly vs monthly.” Before 2026-10-21 the chart drew a Weekly Wall and a Monthly Wall; those were averages of put-side strikes on one expiration and one blend, and they have been retired in favor of the levels above.
Two questions, one read
The Gamma Flip answers one question: is the water calm or rough? The walls answer the other: how much room is there, and which way is the nearest heavy strike? Ask both and the read on any chart takes about 30 seconds. The nodes and the 0DTE Pin add detail on top of that core read.
Above the flip, between the walls: calm regime with room on both sides. The most constructive picture the framework can show: hedging dampens moves and the nearest heavy strikes are the references, not the problem.
Above the flip, pressing the Call Wall: calm water, but the ceiling is right here. Rallies into the Call Wall tend to stall on first touch — the framework favors patience over chasing into it.
Below the flip, above the Put Wall: rough water with a floor underneath. Moves tend to run harder in both directions; the Put Wall is where price has tended to find buyers if it comes down to it.
Below the flip, through the Put Wall: amplified regime with the floor overhead. The defensive picture. Cash is a position; the framework treats a reclaim of the Put Wall as the first sign conditions have changed.
What each kind of day tends to look like, and why
The Gamma Flip splits every session into one of two regimes. Knowing which one you’re in tells you which playbook to lean on before you look at a single setup.
The regime read
The strip at the top of the Chart compares SPY’s current price with its locked Gamma Flip and refreshes every few minutes. It reads one of three states, and the daily email opens with the same read:
- Positive gamma — SPY is above its Gamma Flip.
- Negative gamma — SPY is below its Gamma Flip.
- At the flip — within about 0.1% of it; neither side has won yet.
The strip is the market’s regime. Every individual ticker has its own flip, and the Gamma State card under its chart gives the same read for that name — a stock can be in negative gamma on a day the index is calm.
Why the regime changes the day
Dealers who sell options don’t want a directional bet, so they hedge continuously. Which way that hedging pushes depends on which side of the flip price is on. Above it, dealers are long gamma and their hedging works like a shock absorber: they sell strength and buy weakness. Below it, they’re short gamma and it works like an accelerator: they buy strength and sell weakness. Same market, opposite plumbing, and on index ETFs that hedging is large enough to shape the tape.
| Positive gamma | Negative gamma | |
|---|---|---|
| What dealers do | Long gamma: they sell into rallies and buy into dips to stay hedged. Their flow leans against the move. | Short gamma: they buy into rallies and sell into dips to stay hedged. Their flow leans with the move. |
| The day tends to look like | Tighter ranges, choppier tape, opening pushes that fade back toward the middle. | Wider ranges, a first leg that extends, sharper drops and sharper squeezes. |
| How the levels tend to behave | Walls and heavy nodes tend to hold on the first touch. Price often drifts toward the 0DTE Pin into the afternoon. | A break of a node or wall tends to travel to the next heavy strike. The Put Wall is a floor to watch, not a floor to assume. |
| Setups that tend to fit | Mean reversion: fading a move into a wall or heavy node back toward the middle; treating an opening-range break with suspicion until it holds. | Continuation: going with a decisive break instead of fading it; treating a reclaim of the Put Wall or the flip as the first sign the tape is calming. |
| Why | Every push runs into dealer hedging going the other way, so moves get absorbed. | Dealer hedging adds fuel in whichever direction price is already moving, so moves feed on themselves. |
| Risk | Ranges are tighter, so stops can usually sit closer to the level. | Ranges are wider, so the same position size carries more risk. Size accordingly. |
At the flip
When price sits on the flip, the dampening and amplifying sides of the book are roughly balanced. Days that open here are often indecisive early and then pick a side; the next decisive move away from the flip is the read. Until it comes, there is less edge in either playbook.
Putting it with the walls
The regime tells you how price tends to treat a level; the walls and nodes tell you where the levels are. In positive gamma a test of the Call Wall is more likely to stall and the middle of the range is home. In negative gamma the same test is more likely to resolve one way or the other, and the next heavy strike past it is where the move tends to look for its next stop. Section 06 above maps the four combinations.
The money behind the levels
Everything above tells you where the levels are. The GEX views answer the next question: how much hedging money actually sits at each strike, and which expiration it belongs to.
The Gamma Map is the GEX-by-strike panel beside the Chart: dealer gamma exposure, in dollars, drawn at every strike near price. Red bars are put-side positioning, green bars call-side; the longer and brighter a bar, the more money is parked at that strike. The walls and the flip are where the bars pile up — the map shows you why a level is a level, instead of asking you to take the line on faith.
How to read the map, in four looks
- Find the biggest bars first. Size is money, and money is obligation. The two or three longest bars near price are where dealer hedging concentrates — price has tended to slow down or fight there, in either direction.
- Then read the color. Green (call-side) bars stacked above price tend to act as a ceiling — dealers sell into rallies approaching them. Red (put-side) bars stacked below price tend to act as a floor — dealers buy as price falls toward them. A big red bar above price or green below is worth noticing precisely because it’s unusual.
- Then the gaps. Where the bars are small or missing, there’s little forced hedging to slow price down — moves through empty zones tend to travel fast. A thin stretch between price and the next big bar is the air-pocket read.
- Then where price sits in the picture. Price grinding just under a heavy bar is a different day than price floating in the middle of nowhere.
The FRONT/FULL toggle on the chart’s map switches between this week’s expiring positioning (FRONT — the day-trading read) and the multi-expiration blend out to 45 days (FULL). When the two disagree, the front is what tends to matter today; the full is what tends to matter this month.
The GEX page shows the same money by strike, filterable by when it expires. Every lock stores a separate ladder for each expiration date, all on one strike grid — so you can filter to This Week, Next Week, monthly OPEX, or any combination of dates, and the bars add up exactly. The same locked levels are drawn on it as dividers, so you can see which strikes they sit on. The day-trading read: this week’s expiring gamma is the positioning that has tended to pin price day to day, while the OPEX bar shows the bigger monthly magnet.
Dealer Flows — vanna and charm
Gamma says what dealers must do when price moves. Two more numbers on the Chart and GEX pages say what they must do when only volatility or time moves — which is most of a session.
Vanna is how much dealer hedging changes if implied volatility moves one point. When the book is short puts (the usual case on the indexes), a drop in implied vol shrinks the dealers’ hedge and the card shows demand — the mechanical bid behind “vol down, market up.” A rise in vol flips it to supply.
Charm is how much dealer hedging changes per day from time decay alone, with the share coming from this week’s expiries called out — that is the part that tends to show up as a steady push into the close, heaviest on expiration days.
Both are hedging arithmetic from the same open interest as the levels, locked with them before the open. They assume dealers are long the calls and short the puts customers hold — the same assumption behind every gamma level, and the reason the numbers are a read on pressure, not a forecast of direction.
What the AI does — and doesn't
The division of labor is strict, and it’s worth being precise about, because most services blur it on purpose.
What the AI does NOT do
- Doesn’t predict prices — it explains what the engine already computed
- Doesn’t pick trades or tell you to buy or sell — ever
- Doesn’t compute the levels — that’s the engine, and it’s deliberately kept separate
- Doesn’t claim to know what happens tomorrow — nobody does, including us
- Doesn’t replace your judgment as the trader
It explains. The decision stays with you — which is exactly how it should work.
A daily workflow
Swing traders use the levels as structure for trades held days to weeks. Day traders use them as a pre-open map: a gamma state and the locked levels, set before the bell, that don’t move during the session. Either way, the routine is the same.
Morning routine (5 minutes)
- Read the regime strip at the top of the Chart first. It sets your posture for everything else — positive gamma (days tend to chop and mean-revert), negative gamma (days tend to trend and swing wider), or at the flip (transition)?
- Check the Dealer Flows cards under the levels — vanna (what dealers would have to do if vol moved a point) and charm (what time decay alone makes them do per day, heaviest into the close). Arithmetic, not instructions.
- Open the Chart on anything you’re considering. Check where price sits relative to its Gamma Flip, Call Wall and Put Wall — and open GEX when you want to filter by expiration and see which expiry is carrying the money.
During the day
- The locked levels don’t move. Watch how price behaves as it reaches one — it tends to slow, stall or accelerate there — and check in at decision points, not every tick.
- Use Ask AI to have a name’s locked levels and gamma state explained in plain English before you size in.
- Set a level alert and let the engine watch for you — an email or Discord ping when price gets within your distance of a level, or when the gamma state flips.
Your levels on TradingView
If you chart on TradingView, the locked levels and the expected-move range can sit on your chart there too, in Trade Tracer’s colors. TradingView indicators can’t reach the internet, so it works by a once-a-morning paste:
- Add the Trade Tracer Levels indicator to your TradingView chart (Indicators → search “Trade Tracer Levels”; it’s invite-only — send us your TradingView username and we’ll add you).
- On the Chart here, pick the ticker and press Copy for TradingView.
- Open the indicator’s settings on TradingView and paste into the Levels box. The lines appear, labeled. Paste again each morning after the new lock.
The paste is plain text (ticker, lock date, the levels) and the indicator refuses to draw if the pasted ticker doesn’t match the chart, so a stale SPY paste never lands on QQQ.
Overnight
- The engine recomputes GEX from the day’s closing options data and re-locks the levels before the next open.
- Review open positions against the new levels. A name that closed below its Gamma Flip is in a different regime than the one you bought.
Sizing is your call, not ours
The platform doesn’t tell you how big to go, and never will. Your size is a function of your account, your risk tolerance, and your conviction in the read. We publish the levels and the gamma state — the decisions are yours. If you’re unsure, default to small until you’ve watched enough cycles to know how the framework behaves in your hands.
The terms that matter
- Dealer gamma
- The aggregate hedging position of options market makers. Because dealers hedge mechanically against the options they hold, their buying and selling either dampens price moves or amplifies them, depending on where price sits relative to their book. Every Trade Tracer level is computed from this data, nightly, from end-of-day options open interest across expirations.
- GEX / The Gamma Map
- GEX is dealer gamma exposure — the dollars of hedging pressure parked at each strike, computed nightly for SPY, QQQ and 400+ names. The Gamma Map is the GEX-by-strike panel on the Chart: red bars for put-side positioning, green for call-side, brighter meaning bigger. The GEX page shows the same money by strike, filterable by expiration, with the locked levels drawn as dividers.
- Vanna
- How much dealer hedging changes if implied volatility moves one point. Shown on the Chart and GEX pages as dollars of demand or supply if vol drops a point; a rise flips it. Hedging arithmetic from the locked open interest, not a direction call.
- Charm
- How much dealer hedging changes per day from time decay alone, with the share from this week's expiries called out — the part that tends to show up as a push into the close. Same locked open interest, same dealer-positioning assumption as the levels.
- Gamma state — Positive · At the flip · Negative
- POSITIVE GAMMA: price above its Gamma Flip. Dealers hedge against the move, so days tend to chop and mean-revert. NEGATIVE GAMMA: price below its Gamma Flip. Dealers hedge with the move, so days tend to trend and swing wider. AT THE FLIP: price sitting on the flip — transition; either side can take it.
- The Gamma Flip
- The regime line — the price where net dealer gamma flips from positive (hedging dampens moves) to negative (hedging amplifies them). Not a directional signal: it reads the conditions, not the lean. Drawn in purple, computed nightly, locked before the open. On deeply one-sided days the chart reports "no nearby flip" rather than manufacturing one.
- The Call Wall
- The strike above price holding the most call gamma across every expiration out to 45 days. Dealers are mostly long those calls, so rallies into it meet dealer selling and have tended to stall there. An actual strike, not an average. Drawn in gold, computed nightly, locked before the open.
- The Put Wall
- The strike below price holding the most put gamma — where the market bought its protection. Price has tended to find buyers near it. An actual strike, not an average. Drawn in teal, computed nightly, locked before the open.
- Gamma Nodes
- The heaviest strikes by total gamma (calls and puts combined) inside the expected-move range, besides the walls, flip and pin. Drawn as solid grey lines, up to five; the thicker the line, the more gamma at that strike. Where price tends to react on the way between the walls.
- The 0DTE Pin
- The strike with the most gamma on the nearest expiration alone — today’s, when the name has one. Price has tended to gravitate toward it into the afternoon; it means nothing tomorrow. Drawn as a dashed pink line.
- Locked
- Every level is computed after the close from end-of-day data and fixed before the open. Levels do not repaint, drift intraday, or get revised after the fact, and they never change during the session.
- Gamma
- How fast an option’s stock-like exposure (delta) changes as price moves. It is the quantity that forces dealers to re-hedge — and because it concentrates around heavily-traded strikes, the forced hedging shows up at specific, computable prices.
- OPEX
- Options expiration. Monthly OPEX is the third Friday of each month and reshapes dealer positioning as contracts roll off. The engine computes across the full expiration surface, so the levels reflect these cycles instead of jumping when a single chain expires.
Trade Tracer provides educational analysis tools for self-directed traders. Nothing on this platform is investment, financial, legal, or tax advice. Past performance does not guarantee future results. Options trading carries substantial risk. You are solely responsible for your own trading decisions.